
What is Aani? The UAE's instant payment system
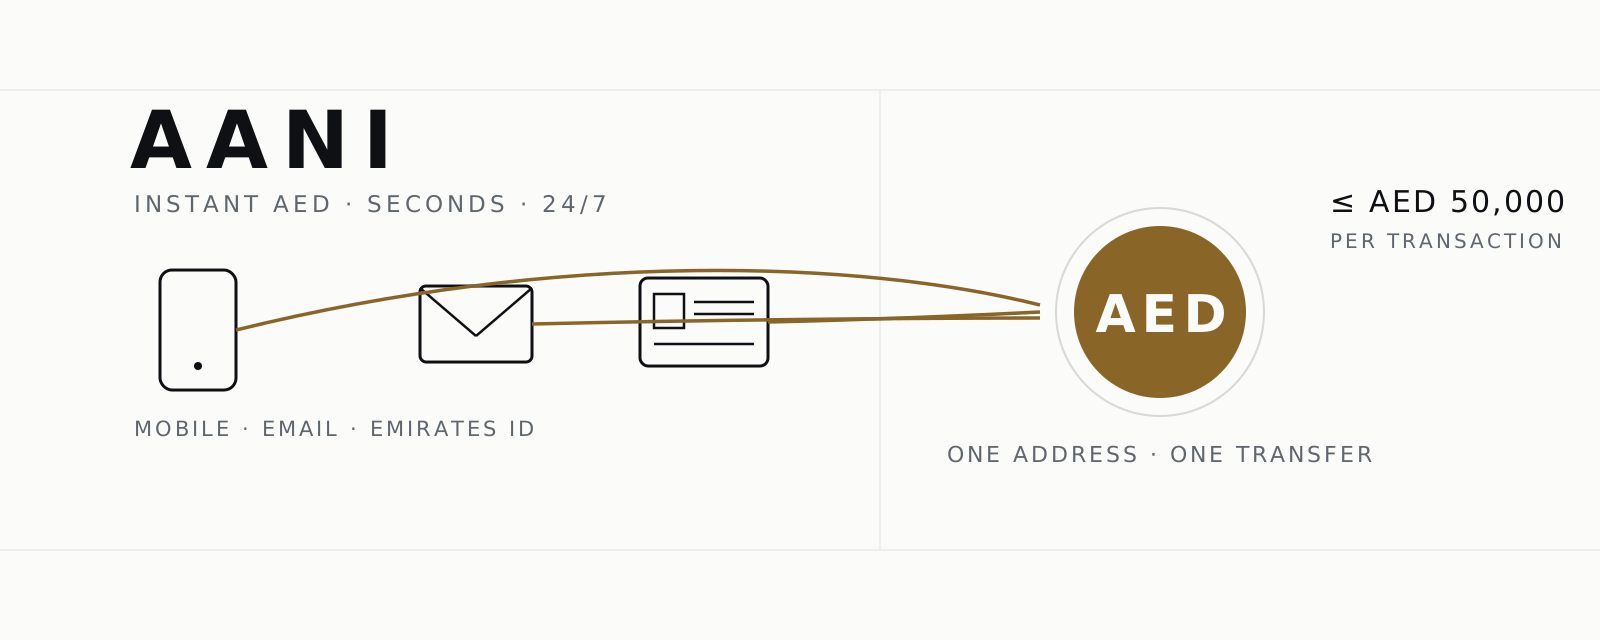
Aani is the UAE's instant payment platform, operated by Al Etihad Payments, a Central Bank subsidiary. It moves dirhams between bank accounts in seconds, 24/7, addressed by mobile number, email or Emirates ID — capped at AED 50,000 per transfer. Here is where it fits when you sell USDT in Dubai.
KEY FACTS
| Operator | Al Etihad Payments (CBUAE subsidiary) |
|---|---|
| Launched | October 2023 |
| Speed | Seconds, 24/7 including weekends |
| Scheme cap | AED 50,000 per transaction |
| Addressing | Mobile number, email, Emirates ID or QR — no IBAN needed |
| Fee | Set by your bank; many charge nothing |
Source: Al Etihad Payments and participating banks' published tariffs, as of September 2026.
How does Aani work in the UAE?
Aani replaces the IBAN with a proxy: you pay to a mobile number, email address or Emirates ID, and the platform routes the dirhams to the recipient's bank account in seconds, around the clock, including weekends and public holidays. Al Etihad Payments launched it in October 2023 on the national Instant Payment Platform; banks offer it inside their own apps and set their own fees. The scheme cap is AED 50,000 per transaction, and a bank's own limit is often lower: some cap mobile-number transfers at AED 10,000. The bank-by-bank picture is in Aani payment limits and crypto settlement.
Aani and UAEFTS are both Central Bank of the UAE infrastructure: Aani is the retail instant layer for everyday amounts, while UAEFTS is the real-time gross settlement system for high-value AED transfers between banks, with no retail cap.
Why it matters when selling USDT in the UAE
Aani is a boundary line: licensed desks settle by UAEFTS to an account in your own name because desk tickets start around 100,000 USDT, far above the AED 50,000 cap. Breaking a large settlement into Aani-sized pieces is the pattern bank monitoring is built to catch.
Illustrative example
You sell 150,000 USDT at the 3.6725 dollar peg: proceeds of AED 550,875. Over Aani that is eleven transfers of AED 50,000 plus one of AED 875, twelve separate inbound payments. Over a licensed desk the same sale is one UAEFTS wire the same business day; at a 0.25% spread the cost is AED 1,377, as of September 2026, per the pricing section.
FAQ
Is Aani free to use?
Aani itself sets no fee; pricing belongs to your bank. Most participating banks charge nothing for Aani transfers as of September 2026, but each bank publishes its own tariff and can change it at any time.
What is the maximum Aani transfer?
The scheme cap is AED 50,000 per transaction. Your bank's own limit sits underneath it and is often lower — some banks cap mobile-number transfers at AED 10,000 while allowing the full AED 50,000 to an IBAN.
Can I receive OTC sale proceeds over Aani?
Desk-size settlements are far above the AED 50,000 cap, so a licensed desk pays by UAEFTS wire to an account in your own name. Aani suits everyday amounts below the desk minimum, not six-figure payouts.
Is Aani the same as UAEFTS?
No. Aani is the retail instant layer running on the national Instant Payment Platform; UAEFTS is the real-time gross settlement system for high-value AED payments between banks. Both are Central Bank of the UAE infrastructure.
Selling above Aani's limit?
IWGT is a VARA-licensed Broker-Dealer in Dubai. All-in spread 0.08–0.40% by ticket size, published openly. AED by UAEFTS the same business day to your own account, once onboarding is done.
SOURCES
- Al Etihad Payments — operator of Aani, accessed 10 September 2026.
- Central Bank of the UAE — payment systems (UAEFTS), accessed 10 September 2026.
- IWGT published pricing bands and onboarding requirements — IWGT published pricing bands, September 2026.
This guide is informational and is not legal, tax or investment advice, nor an invitation to buy or sell any virtual asset. Rules and figures are as of September 2026 — re-check the sources before acting. Virtual assets may lose their value in full or in part and are subject to extreme volatility.